Updated October 22, 2026 | AltaVida Capital
The Short Answer
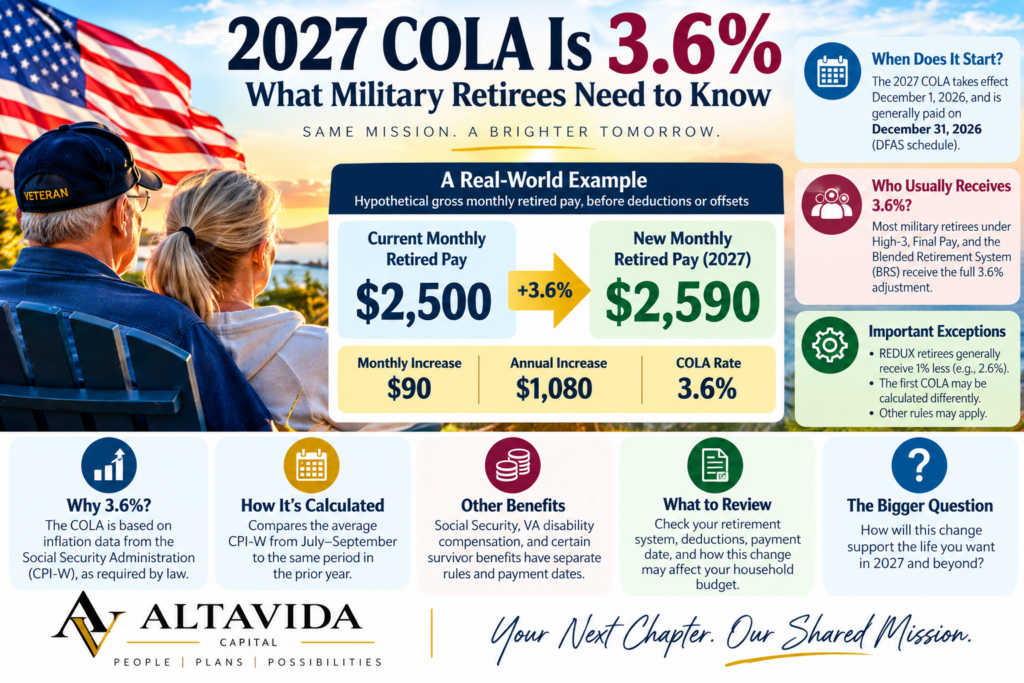
The 2027 (COLA) cost-of-living adjustment is 3.6%. The Social Security Administration announced the increase on October 14, 2026.
For most military retirees receiving retired pay under the High-3, Final Pay, or Blended Retirement System (BRS), the annual COLA follows the same inflation-based percentage. However, special rules can affect retirees receiving their first COLA or those covered by the REDUX retirement system.
The military retired-pay adjustment takes effect December 1, 2026, under the established statutory process. Eligible military retirees will generally see the adjustment in their December 31, 2026, payment.
But what does that increase actually mean for a household’s monthly income?
How Much More Could You Receive?
Consider a hypothetical military retiree receiving $2,500 in gross monthly retired pay.
A full 3.6% adjustment would produce:
- Current gross monthly retired pay: $2,500
- COLA increase: $90
- New gross monthly retired pay: $2,590
- Annualized increase: $1,080
This illustration uses hypothetical gross monthly retired pay before taxes, deductions, or offsets. It assumes the retiree qualifies for the full 3.6% increase.
Actual payments depend on the retirement system, the date retirement began, applicable adjustments, and individual deductions.
A higher gross benefit also does not necessarily produce an identical increase in the amount deposited into a bank account.
Why Is the 2027 COLA 3.6%?
COLA is designed to help eligible benefit payments keep pace with changes in consumer prices.
The Social Security Administration calculates its annual adjustment using the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W), published by the Bureau of Labor Statistics.
The calculation compares the average CPI-W for July, August, and September with the corresponding average from the last year in which a COLA became effective.
The comparison for 2027 produced a 3.6% adjustment.
Military retired-pay COLAs generally follow this statutory inflation adjustment, subject to the rules applicable to the member’s retirement system.
The purpose of COLA is to help preserve purchasing power. It is not a bonus or a guarantee that every household expense will increase by exactly the same percentage.
Do All Military Retirees Receive 3.6%?
No. The retirement system and timing of retirement matter.
High-3 and Final Pay: Most established retirees under these systems qualify for the full applicable annual COLA. Special first-year calculation rules may apply.
Blended Retirement System (BRS): Eligible retirees generally receive the full annual COLA rather than the reduced REDUX adjustment.
REDUX/CSB: Retirees who elected the applicable Career Status Bonus/REDUX arrangement generally receive an annual COLA one percentage point below the standard adjustment when the standard increase exceeds 1%. A standard 3.6% adjustment would therefore generally mean 2.6% under this rule, with other statutory provisions potentially affecting individual calculations.
Recently retired service members: The first COLA may be calculated differently based on when retired pay began and the retirement system involved. A new retiree should not assume that the full headline percentage applies to the first adjustment.
For the rules governing these distinctions, see 10 U.S.C. § 1401a.
When Will the Increase Appear?
For military retired pay, the annual statutory COLA takes effect December 1, 2026.
For eligible military retirees paid on the regular DFAS schedule, the December retired-pay entitlement is scheduled for payment on December 31, 2026.
Social Security follows a different payment schedule. Its 3.6% COLA begins with benefits payable in January 2027.
These payment dates are important for households receiving income from more than one benefit program.
A retiree who receives military retired pay, Social Security, or other government benefits may see adjustments reflected on different dates.
What About Survivor Benefits, CRDP, and CRSC?
Not every benefit associated with military retirement follows precisely the same payment rules.
Survivor Benefit Plan (SBP): Eligible survivor annuities are subject to applicable COLA provisions. An individual survivor’s payment may also reflect other relevant benefit and eligibility rules.
Concurrent Retirement and Disability Pay (CRDP): The amount payable depends on the retiree’s eligibility, military retired pay, VA disability compensation, and applicable concurrent-receipt rules.
Combat-Related Special Compensation (CRSC): Payments are determined under separate eligibility and calculation provisions. A headline retired-pay COLA should not be treated as proof of an identical increase in every CRSC payment.
Retirees and survivors should review their official benefit statements rather than assume all payment categories will change by the same dollar amount.
Will VA Disability Compensation Also Increase?
VA disability compensation uses cost-of-living provisions tied to Social Security adjustments, under applicable federal law.
With the 2027 COLA Social Security at 3.6%, eligible veterans and families can review VA announcements and official compensation tables for the corresponding benefit changes.
Congressional action and the applicable statutory authority are important when evaluating annual VA compensation adjustments. Readers should rely on enacted legislation, official VA rate tables, and agency implementation notices rather than treating a proposed bill or legislative announcement as a completed change in law.
The VA benefit calculation is separate from the calculation of military retired pay. A person receiving both benefits should review each payment individually.
Why a 2027 COLA Increase May Not Feel Like More Money
Imagine a retired military household reviewing its January budget.
Its gross retired pay has increased, but so have grocery costs, insurance premiums, utilities, or other household expenses.
That household may receive a larger monthly payment while still facing pressure from everyday expenses.
A COLA adjustment measures changes in a broad price index. Individual spending patterns can be different.
That makes the annual adjustment a useful opportunity to review household income and expenses.
Five Questions to Ask Before 2027 COLA
- Which military retirement system applies to me? High-3, Final Pay, BRS, and REDUX can have different COLA implications.
- Am I receiving my first COLA? The timing of retirement may affect the initial increase.
- What will my new gross and net payments be? Compare official statements and deductions rather than relying only on a percentage.
- Do I receive other benefits with separate payment schedules? Military retired pay, Social Security, VA compensation, and survivor benefits may not be deposited on the same date.
- Has my household budget changed? Review expenses, income needs, and upcoming financial obligations.
These questions can help a military retiree prepare for the new year without assuming one adjustment solves every retirement-income concern.
The Bigger Question
A 3.6% increase is measurable.
But what matters to a household is what that increase allows it to do.
Does it help cover rising costs? Create room in the monthly budget? Or reveal expenses that need closer attention?
Sometimes the most useful question is not simply, “How much more will I receive?”
It is:
“What will this change mean for the life I’m planning?”
At AltaVida Capital, we believe financial education begins with better questions, clear information, and meaningful conversation.
Understanding how benefits work is one part of preparing for retirement. Understanding how those benefits fit into everyday life is another.
Official Sources
- Social Security Administration — 2027 COLA announcement: https://www.ssa.gov/news/en/press/releases/2026-10-14.html
- Social Security Administration — 2027 COLA information: https://www.ssa.gov/news/en/cola/
- United States Code — 10 U.S.C. § 1401a, military retired-pay COLAs: https://uscode.house.gov/view.xhtml?req=(title:10%20section:1401a%20edition:prelim)
- Defense Finance and Accounting Service: https://www.dfas.mil/
- Department of Veterans Affairs — Disability Compensation: https://www.va.gov/disability/compensation-rates/
Educational disclosure: This article provides general information for educational purposes only. It does not constitute individualized financial, tax, or legal advice, an insurance recommendation, or a determination of benefits eligibility. Benefit amounts, dates, and eligibility depend on applicable laws and individual circumstances. Consult the administering agency for official benefit determinations.
AltaVida Capital | People | Plans | Possibilities